Top Glove reaches 92 sen as research houses keep negative ratings
Quarterly net profit rose to RM157.6 million, while analysts cited excess glove supply and potential cost increases as risks to the recovery.
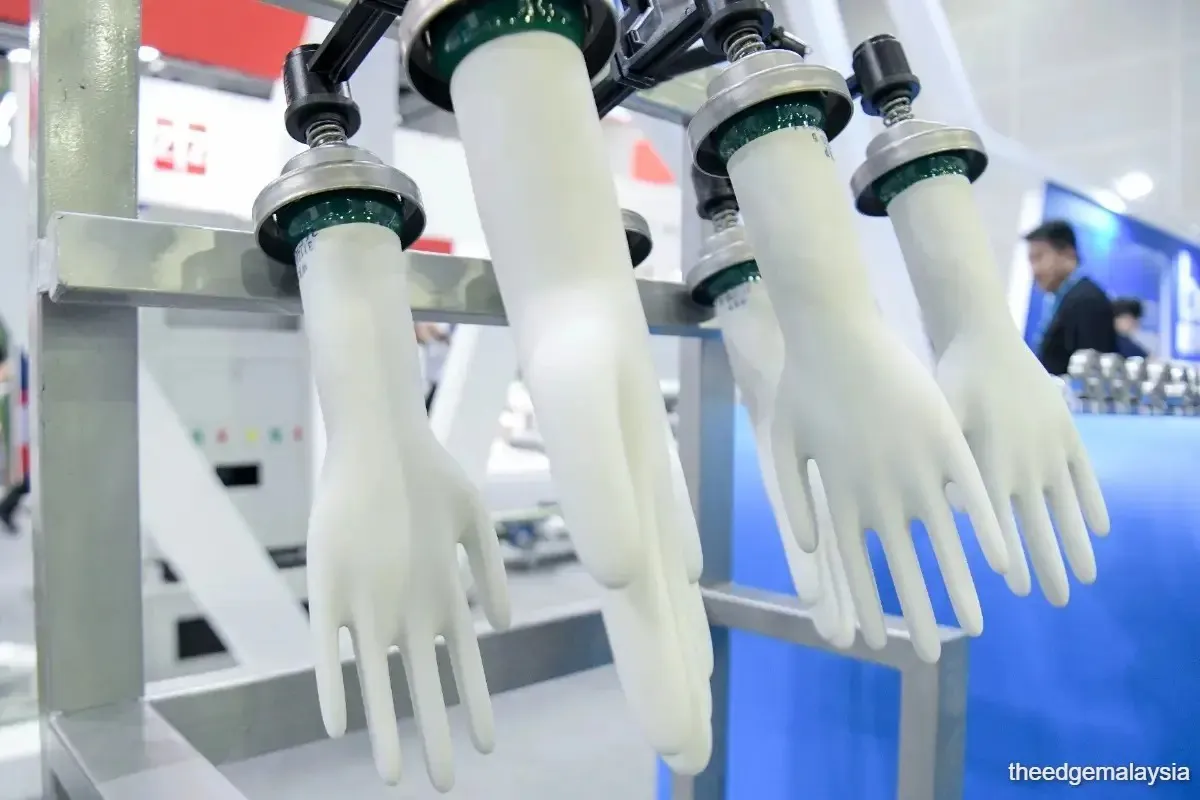
Top Glove Corp Bhd shares touched 92 sen during early trading on Oct 7 following its 4QFY2026 results, which showed net profit of RM157.6 million. PublicInvest Research and CIMB Securities kept their negative recommendations despite increasing their target prices.
With turnover exceeding 162.52 million shares, Top Glove ranked as Bursa Malaysia’s most actively traded stock at the reporting time. Supermax Corp Bhd gained as much as five sen, reaching 51 sen on volume of about 52 million shares. Kossan Rubber Industries Bhd retreated from RM1.30 to RM1.22, leaving it down three sen or 2.4%.
Top Glove’s quarterly revenue reached RM1.25 billion, a year-on-year increase of 39.7%, helped by greater sales volumes and higher blended average selling prices. Net profit for FY2026, which ended on Aug 31, 2026, totalled RM357.4 million. However, fourth-quarter sales volume fell 7.0% against the preceding quarter amid weaker latex glove demand.
PublicInvest Research raised its target price from RM0.59 to RM0.69 but retained an “underperform” rating. CIMB Securities moved its target from RM0.63 to RM0.70 while maintaining “reduce”.
CIMB Securities said earnings had likely reached their peak as selling prices normalised after June 2026. It pointed to competition from Chinese manufacturers and global capacity exceeding 500 billion pieces, versus estimated demand of approximately 400 billion pieces for 2026-2027F.
The research house projected that October 2026 natural gas tariff increases of 30% to 39% would add 2% to 3% to costs per carton. A potential rise in the minimum wage to RM1,900 per month could increase production costs by another 1%.
Top Glove’s year-end balance sheet showed net cash of RM141 million, reversing the previous year’s RM267 million net debt position. PublicInvest Research said further rerating depended on evidence that improved pricing and utilisation could sustain stronger returns amid oversupply.